Venezuela 2026 State Collapse: The Decapitated State

Updated: 7 days ago
Originally published Jul 23, 2026 · Updated: October 1, 2026
Contents
Key Takeaways
The Custodial Vacuum. The operation removed a head of state and preserved everything else. The January capture ended the Maduro presidency, but no successor was elected, no apparatus was dismantled, no constitutional pathway was installed. Nine months on, the doctrinal vacuum is no longer a phase — it is the governing condition, and the doctrine that has emerged in practice is custodial: manage the vacuum, monetise the ground. Two rounds of US-sponsored talks have now produced judicial-reform accords, not a settlement; it is highly likely that the custodial equilibrium persists through 2027 unless rupture arrives from outside the negotiating table.
The Refinanced State. The zombie state was not cured in 2026. It was refinanced. The late-August oil agreement converts Washington from enforcer to equity holder in the republic's energy estate — majority participation in roughly a fifth of the world's largest reserves, hundred-year concessions, a Pentagon procurement option, and a landlord whose returns depend on nothing being decided. The United States did not merely decline to force elections; it acquired a financial position whose value depends on their continued deferral. The regime-preservation logic and the shareholder logic now point the same direction.
The Absent State. The earthquake was a governance audit, and the armed forces failed it. A command-and-control failure — not a resource constraint — paralysed the response to the nation's deadliest natural disaster in modern history, while the death toll climbed past six thousand, the United Nations placed direct damage near $37 billion, and the humanitarian appeal had reached barely a quarter of its target population six weeks in. The audit found institutional capacity absent, not merely degraded. There is a realistic possibility that a secondary displacement wave keeps the emergency acute into 2027.
The Bilateral Clock. The transition is no longer a constitutional question. It is a bilateral one. Elections are discussed in Washington in 2028–2030 horizons; the opposition leader who won the 2024 credibility contest remains barred, exiled and uninvited to the very talks meant to settle her country's future. It is highly likely that no presidential election is held before 2028 under any configuration currently visible.
Portfolio-level. The investable distinction for the next eighteen months is no longer between transition and stagnation — it is between assets priced off reconstruction activity (energy services, licensed operators, procurement flows) and assets priced off governance quality (sovereign claims, long-dated concessions, population-dependent demand). The first class trades on the Chevron $7 billion programme and the concession architecture already in force; the second carries a compounding liability that no license converts. Organisations with exposure should treat the Hormuz theatre and the legal durability of the hundred-year concessions as the two repricing triggers — not the electoral calendar, which has been decommissioned as a variable.
1. The Extraction Precedent: Regime Decapitation Without a Doctrine
The January operation was not an intervention in the country's politics. It was a subtraction from them. On 3 January 2026, US special forces conducted a nighttime raid on Caracas, capturing President Nicolás Maduro and First Lady Cilia Flores — explosions reported around Fuerte Tiuna, the republic's largest military complex — and transporting both to New York. It was the first American military incursion on Venezuelan soil in the nation's history, a fact that has reshaped the hemisphere's strategic landscape regardless of how the administration frames it.
The legal sequel has unfolded with a precision the political sequel never acquired.
Appearing in Manhattan federal court, the former president described himself as a "prisoner of war" and later as "still the president of my country." On 22 July, US District Judge Alvin Hellerstein set the trial for 1 June 2027 on drug-trafficking and narco-terrorism charges. On 2 September, defence attorney Barry Pollack — who previously represented Julian Assange — filed the anticipated motion to dismiss: the prosecution, he wrote, violates "the absolute immunity from criminal jurisdiction to which heads of state and foreign officials acting in their official capacities have been entitled for hundreds of years" (Reuters, 2 September 2026; Washington Post, 3 September 2026). Prosecutors must respond by 2 October, and Hellerstein has scheduled the dismissal hearing for 17 November; Flores has filed a separate motion targeting counts two through four on spousal-immunity grounds (JURIST, 4 September 2026). Six US-based experts in international law consulted by Reuters judged the relevant precedents unfavourable to the defence — and on that record, it is highly unlikely that the immunity motion succeeds before the June 2027 trial window.
The instrumental logic — removing a narco-authoritarian leader to open political space — was coherent in outline. The execution produced the opposite. The United States removed the head of state but did not install a successor, did not dismantle the Chavista security apparatus, did not reform PDVSA's governance, and did not establish a constitutional pathway to elections. What it installed was an acting president already inside the regime, representing continuity with the very apparatus the operation was designed to dismantle. This is regime decapitation without regime change — neither the Libya model of collapse following removal, nor the Panama model of restoration following occupation, but something new: the extraction of a sovereign under military force, the preservation of the surrounding state, and the indefinite deferral of a settlement. The doctrinal vacuum is itself a risk — because every actor in the region is now reading the precedent for their own file, as our Cuba energy-collapse analysis of the intervention-pretext dynamic documents in detail.
For organisations with contracts keyed to sovereign counterparties: treat ministries, regulators and state enterprises as transmission mechanisms for a survival logic rather than decision-making bodies; obtain jurisdiction-shift and successor-government clauses in every agreement signed before the next sovereign reckoning — the June 2027 trial date and the appeal clock it starts are your legal-risk horizon; and assume the case generates collateral litigation over seized assets for years.
2. The Zombie State: Preservation Logic and the Blocked Transition
The republic is not governed. It is occupied by its own remainder. Delcy Rodríguez assumed the acting presidency under constitutional provisions the Chavista apparatus itself drafted — unelected, unselected by any transparent process, the instrument through which the regime survived the decapitation of its leader. Her conduct since January confirms that her mandate is preservation, not transition: pro-Maduro hardliners retained in key positions, the post-earthquake state of emergency invoked to defer any electoral timetable, and the return of opposition leader María Corina Machado from the United States blocked with administrative and security barriers in June.
The critics' label — the "zombie state" that lurches forward, performing the functions of governance at a minimum level while consuming resources without producing outputs — is analytically precise. The military cannot deploy effectively; the oil infrastructure cannot produce at capacity; the political system cannot hold elections; the humanitarian apparatus cannot respond to a natural disaster. What has changed since summer is that the condition stopped being a stigma and became a business model. Time Magazine described the government's submission to Washington as "a docility that no Venezuelan government has displayed toward a foreign power since the republic's founding in 1830."
The September record is the confirmation — and it now extends into negotiations. President Trump, asked on 2 September about elections, answered that the country is "not ready" — while praising Rodríguez as "highly respected" (Al Jazeera, 2 September 2026; CNN en Español). Reporting on the administration's internal deliberations puts the timelines circulating in Washington at 2028–2030 (Politico, 2 September 2026). The two rounds of US-backed talks, first convened in August and resumed 15 September at the Meliá hotel in Caracas, closed on 25 September with preliminary agreements to work toward reform of the Supreme Court of Justice and to loosen administrative restrictions on several opposition-aligned news outlets — accords on process, not on power. The government delegation was led by National Assembly chief Jorge Rodríguez; the opposition by Dinorah Figuera, who led the last internationally recognised parliamentary bloc; Machado was not invited to the table.
The State Department has endorsed the process as a "unique opportunity" for a "political transition" — language that treats the transition as an aspiration with no date attached (AP, 26 September 2026; Al Jazeera, 26 September 2026). Machado, meanwhile, announced her return to the country and a nationwide push for a presidential election, while administration officials remain divided over whether she could govern the institutions the apparatus still holds — and the US Senate has scheduled an urgent committee meeting placing her return and eligibility at the top of the agenda (Wall Street Journal, as reported 21 September 2026). Foro Penal counts at least 391 political prisoners still held (Al Jazeera, 14 August 2026). Approximately 100 protesters gathered in Caracas demanding an electoral timetable; the scale of that mobilisation, in a country of 28 million, measures the distance between democratic aspiration and operational capacity.
The pattern is structural, and it now runs through Washington rather than around it. It is highly likely that no presidential election is held before 2028 under any configuration currently visible — the emergency framework supplies the legal cover, the oil agreement supplies the financial incentive for deferral, and the administration's own stated timelines bracket the question beyond the scenario horizon. The variable that could break the deferral is external, not domestic: a political recalculation in Washington or a rupture within the apparatus itself.
For organisations with political-risk exposure keyed to electoral timelines: remove elections from your base-case planning entirely for 2027; shift monitoring weight to the negotiation rounds (attendance, agenda, US sponsorship intensity) and to the trial docket in Manhattan, which remains the only institutional clock running; and treat any signal of an intra-apparatus split — high-level defections, security-force friction — as your leading indicator of an unscheduled transition.
3. The Seismic Inflection: An Audit the Armed Forces Failed
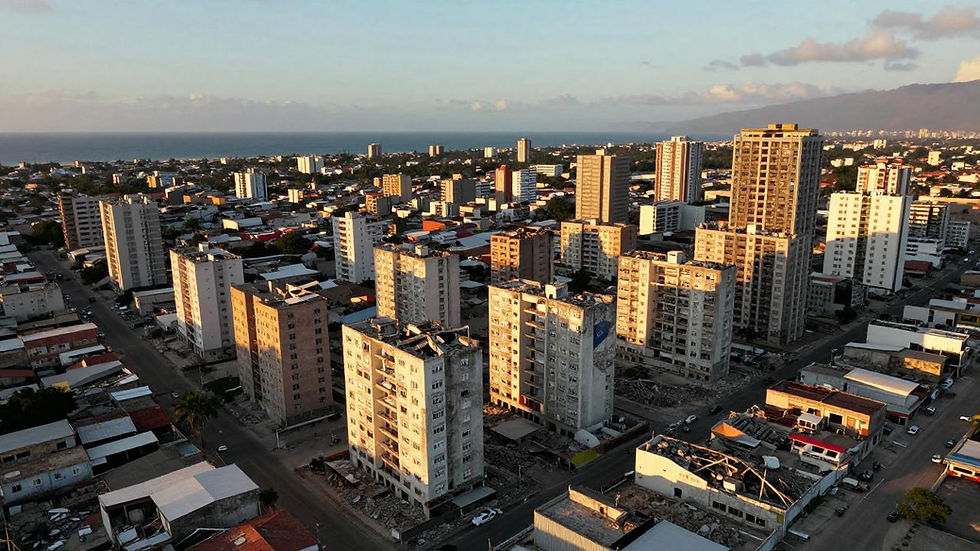
An earthquake is a state examination administered without notice. The twin shocks of 24 June — magnitudes 7.2 and 7.5 striking the northern coast near La Guaira — were the largest natural disaster in the nation's modern history, and the response was a clinical exposure of institutional collapse. The death toll, which stood at 5,069 on 18 July, had climbed past 6,125 by early August as debris clearance progressed, with more than 29,000 people carried on a missing-persons registry compiled by NGOs tracking the recovery (IFRC situation reports, August 2026; Good Neighbours, 7 August 2026). The official figures — 16,740 injured, 856 buildings damaged, 190 collapsed, 1,331 aftershocks recorded — continue to rise, and an initial United Nations assessment put direct damage to housing and infrastructure at approximately $37 billion (IRC, 8 September 2026). The flash appeal targets 1.3 million people with a $298 million requirement, against the 7.9 million already in need of humanitarian assistance before the ground moved (OCHA flash update, 23 July 2026); UNICEF counts 1.8 million people in need post-quake, including 680,000 children, against a $65.7 million earthquake requirement inside its $137.6 million country appeal (UNICEF, 28 July 2026).
The diagnosis matters more than the damage. Citing eight sources familiar with the response, Reuters reported that the military's deployment was hindered by delayed orders from senior commanders, confusion over who was responsible for coordinating the crisis, and a lack of relevant equipment — and that active-duty officers, diplomats and officials confirmed the thin presence of security forces in the crucial first days was not a resource constraint but a command-and-control failure. A state whose army cannot deploy in its own capital region during its deadliest disaster cannot coordinate an evacuation, cannot secure critical infrastructure, cannot manage a mass-casualty event, cannot respond to a security incident. The capacity that underpins investor confidence, operational continuity and contractual enforcement has been shown to be absent — not degraded, absent.
The independent record now fills the space the official one avoids. Tom Fletcher, the United Nations Emergency Relief Coordinator, said more than 50,000 people remained unaccounted for in the days after the shock (27 June 2026); by late August, NGO-compiled registries still counted some 29,000. The Pan American Health Organization coordinates an Emergency Operations Centre network of 110 organisations co-led with the IRC; MSF and the IFRC maintain field tents in La Guaira; World Central Kitchen mobilised within hours on pre-existing partnerships, its founder pledging $1 million personally. Coverage is the revealing metric: of the 1.3 million people targeted by the flash appeal, fewer than 364,000 had been reached with assistance and essential services by late August (OCHA Situation Report No. 34, 27 August 2026) — a coverage ratio near 28% six weeks after the first shock, with the response now formally shifting from emergency relief toward long-term recovery (Direct Relief, 24 September 2026).

The New Humanitarian's field assessment located the failure precisely: the disaster "underscored the cumulative consequences of institutional failures, low emergency preparedness, widespread corruption and poor humanitarian coordination" (28 July 2026). Even the relief itself became contested terrain: opposition leaders Heidy Loicett and María Oropeza accused the administration of "political persecution" in its handling of aid, while the US chargé d'affaires John Barrett pronounced the government "fully compliant" with American requests (July 2026) — domestic critics and the occupying power describing the same weeks in opposite adjectives.
The international response drew the geopolitical geometry in relief. The United States delivered over 1.5 million pounds of humanitarian aid, with American soldiers on the ground directing logistics at Simón Bolívar Airport; Israel deployed an IDF search-and-rescue delegation received by Rodríguez herself before departure. China sent a single Air China cargo flight, landing on 6 July — nearly two weeks after the quakes. Washington is physically present; Beijing is symbolically present; and the government in Caracas presided over neither. It remains a realistic possibility that a secondary displacement wave — households leaving structurally condemned housing through the remainder of 2026 — keeps the humanitarian emergency acute into 2027, compounding the migration pressures assessed below.
For organisations with personnel, logistics or duty-of-care exposure: plan on the absence of state emergency response as a permanent operating condition — self-sufficient medical evacuation and communications for all expatriate staff; audit facility siting against seismic zones around La Guaira and the coastal corridor before any reconstruction-related commitment; and treat NGO and IFRC field reporting, not government statistics, as your ground truth.
4. The Oil Prize: 303 Billion Barrels Change Custody
The prize was never in doubt; its custody was. The republic holds the largest proven crude reserves on Earth — approximately 303 billion barrels, per the US Energy Information Administration — and 2026 was the year the ownership question was answered, not by the market but by treaty-like fiat. Production told a story of recovery within constraints through mid-year: exports rose to 1.25 million barrels per day in May, a third consecutive monthly increase and a projected 22% rise from the 1.12 million bpd of late 2025 (CNBC, 31 August 2026), with US-bound imports running at roughly 135,000 bpd and port delays of up to thirty days constraining loadings. The recovery then stalled exactly where it started: national output measured 1.20 million bpd in July and 1.201 in August, up from roughly 1 million at the start of the year but nowhere near the oil ministry's 1.37 million year-end projection (Trading Economics, September 2026; CNN, 2 September 2026). The Treasury's 13 February general license had already permitted Chevron, BP, Eni, Shell and Repsol to resume operations; Chevron, the only American major actively producing, accounted for roughly a quarter of output while its own shipments slipped from 308,000 bpd in April to 269,000 in May, with global traders Vitol and Trafigura absorbing the difference. By 31 July, the company was producing some 280,000 bpd, up 15% (company disclosure, 31 July 2026).
Then the framework changed. On 28 August, the administration announced an agreement granting US-majority participation over roughly 65 billion barrels of the national reserves — about a fifth of the total — through hundred-year concessions on 17 oil fields, executed through North American Blue Energy Partners, a Barbados-headquartered vehicle controlled by entrepreneur Alejandro Betancourt López (White House fact sheet details; Wall Street Journal and CNN, 31 August 2026). The Pentagon participates through its Office of Strategic Capital — reported variously at a 35% stake per White House details and at 55% per Fortune's reconstruction, a discrepancy the Defence Department's own spokesman deepened by denying that the office "takes stakes" at all (CNBC, 5 September 2026; Fortune, 1 September 2026) — and holds a right to purchase crude at cost of production.
The contest does not stop at percentages: NPR subsequently corrected its own description of the deal, noting that Washington secures a share of the output of the seventeen fields rather than a majority stake in them (NPR, 25 September 2026). The transaction's timing is inseparable from the Iran war: with benchmark crude near $92 and strategic reserves drawn down, energy security economics did the negotiating. On 2 September in Caracas, Energy Secretary Chris Wright oversaw the companion Chevron deal: $7 billion over five years, additional Orinoco Belt acreage including two newly assigned fields, a stated 600,000 bpd production target, production costs below $20 per barrel, and an enhanced stake in the Petroindependencia joint venture raised from 35.8% to 49% in April (Chevron corporate statement, 2 September 2026; Reuters, 31 August 2026). Rodríguez herself has described the arrangement as running twenty-five years with a national target above 1.5 million bpd — a horizon she did not hold a mandate to promise (Washington Times, 30 August 2026). In the assessment of Eurasia Group's Gregory Brew, the concession architecture is "probably unprecedented" in the modern era and, in his word, colonial (Fortune, 1 September 2026).

Two structural caveats bound the prize. First, the recovery narrative obscures what Forbes, the Wall Street Journal and multiple analysts have long underscored: the collapse began with PDVSA's internal decay — political purges, technical-staff losses, infrastructure deterioration — and sanctions relief slows decline without reversing institutional damage; Rystad Energy puts the return to the 3-million-bpd pre-crisis level at sixteen years and $183–185 billion of investment (Rystad Energy, January 2026; reiterated in current coverage). Second, the concessions carry a latent legitimacy problem that no market model prices: an agreement signed by an unelected caretaker with century tenures is a standing target for any successor government with a mandate and a grievance — precisely the legal risk Machado's opposition has already flagged publicly.
The exporting machine has a mirror image, and it is broken. The Paraguaná Refinery Complex — Amuay and Cardón, 955,000 barrels per day of nominal capacity, once among the largest in the world — runs at a fraction of that figure: a flexicoker blackened and idle, open-air settling pools nearly full, residues seeping into pipelines and valve stations, per employees interviewed by Reuters, one of whom described the installation as simply "ugly and rusty" (Reuters, 29 July 2026). Small repairs had recovered roughly 20,000 bpd of processing capacity each at El Palito and Amuay, per PDVSA refining vice-president Jovanny Martínez at an April conference — against experts' estimate of more than $20 billion for full restoration. The earthquakes spared the refineries physically but diverted attention and resources from any restart calendar. The result is the rentier inversion in its purest form: a state exporting raw crude while importing gasoline for its own market, every litre of domestic fuel a logistics dependency stacked on top of the port delays. The resource-sovereignty collision this represents for the wider extractive map is the same fault line our critical minerals assessment tracks across jurisdictions.
Given the licensed capacity in place and the pace of Chevron's commitment, it is likely that production oscillates in a 1.2–1.4 million bpd band through 2027 — below ministry forecasts, above the degeneration path — with the 600,000-bpd Chevron target the bellwether that separates reconstruction thesis from reconstruction theatre.
For organisations with energy exposure: treat the 13 February licenses as settled and the 28 August concessions as contestable — sequence investments so that license-derived value accrues before any concession-dependent commitment; benchmark any contract pricing against the Pentagon's cost-of-production purchase right, which establishes a state-backed price floor unavailable to private counterparties; and stress-test every project model against the 2030 US strategic-reserve replenishment calendar.
5. The Sanctions Lattice and the Andean Contagion
The sanctions regime is no longer a list of prohibited transactions. It is a lattice — the country, Iran, Russia, Syria and China threaded under overlapping legal frameworks, with Treasury layering transaction-specific authorisations atop broad prohibitions, creating what Bloomberg Law describes as "a compliance environment where the legal framework remains restrictive, but the practical rules governing what's allowed are fluid and difficult to interpret." The new oil architecture does not dissolve the lattice; it threads it: every licensed operator, trader and financier in the reconstruction now navigates an environment where authorisations and prohibitions coexist at the level of individual transactions, and where exposure here intersects with Iran, Russia and China exposure in ways that are legally interconnected and operationally opaque. Compliance teams cannot treat these as separate jurisdictions.
The second contagion channel is demographic. Almost 7 million people — roughly a quarter of the pre-crisis population — remain displaced outside the country, one of the world's largest displacement crises (UNHCR Global Trends, June 2026), hosted principally by Colombia, Brazil, Ecuador, Peru and Chile. The earthquake layer compounds the arithmetic: 6.7 million affected domestically, over a million targeted by the flash appeal, and with the households holding the resources to move having largely already done so, the residual population is the least mobile and most aid-dependent. The receiving states strain accordingly — the border-infrastructure, labour-market and social-cohesion dynamics we assess in our Colombia, Brazil and Ecuador reports — while El Niño conditions compound drought, wildfire and water stress across the host economies. The contagion is not hypothetical; it is an observable pattern radiating from the 2026 collapse into Andean and Southern Cone operating environments.
Beneath the lattice, the household economy is dollarised. Close to nine million citizens — roughly a quarter of the population — live abroad (Inter-American Dialogue, August 2026), and the diaspora sends back between $3 and $5 billion a year: for some 29% of households up to 80% of the beneficiary family's monthly income, and the largest flow of hard currency after oil (Wilson Center; Inter-American Dialogue, August 2026). Sanctions relief has moved much of this flow into licensed transfer channels, helping narrow the official-parallel exchange-rate gap from 73% to 13% in eight months (Inter-American Dialogue, 19 August 2026). The channels remain hybrid — Zelle transfers and groceries bought remotely and delivered in kind — so the flow is both resilient and nearly invisible to formal accounting. And the corridor now runs both directions: UNHCR reports growing numbers returning from Ecuador, Peru and Colombia — pushed by hardening immigration policies in host countries — straining "already overstretched" resources on arrival (OCHA, 2026). The compliance calendar has a specific date attached: the Treasury's humanitarian general license for disaster assistance expires on 23 October 2026 (US State Department, August 2026) — a deadline well inside the recovery horizon it underwrites.
Beijing's position threads the lattice's third strand. The China Development Bank holds an estimated $17–19 billion in outstanding principal from oil-for-loans programmes (AidData research), and Chinese refiners have been buying 50–89% of the exportable crude in recent months (Reuters analysis, 4 September 2026) — flows that kept PDVSA solvent through the sanction years. The new architecture directly challenges both: redirected sales would strip Beijing of a discounted crude source and of the repayment mechanism for a multi-billion-dollar loan portfolio, a cost not currently priced into market models. Given that the concessions preclude Chinese participation in the fields that matter, it is likely that Beijing pivots from purchase-led to leverage-led engagement through 2027 — debt restructuring, infrastructure positioning, and diplomatic patience with a post-settlement optionality.
For organisations with supply-chain, staffing or lending exposure across the Andean corridor: build scenario spreads around a renewed secondary migration wave in H1 2027 timed to reconstruction labour demand rather than humanitarian catastrophe; screen every counterparty in the energy reconstruction chain for designation-list movements quarterly — the lattice's transactional fluidity makes last quarter's cleared status an unreliable guide; and treat host-country absorption capacity — Colombian border provinces above all — as the variable that converts displacement into regional operational risk.
6. Beijing's Ledger and the Anti-Access Network
China did not lose the country in January. It lost the asset. Two decades of oil-for-loans agreements, discounted crude purchases and UN-aligned diplomacy had built a strategic foothold that served energy security, geopolitical positioning, and the demonstration that an alternative to US-led financial architecture existed for sanctioned states. The January operation, the assertion of American control over oil sales "indefinitely" in Energy Secretary Wright's February formulation, and now the concession architecture have stripped it of the asset itself — while leaving Beijing's $17–19 billion CDB ledger and its regional networks entirely intact. The single Air China relief flight of 6 July, landing under the eyes of American soldiers directing logistics, was less a humanitarian gesture than a signal that the interests survive the asset transfer; the strategic question is not whether Beijing contests US dominance directly — it lacks the military proximity and institutional depth — but whether it converts loan leverage into infrastructure equity, debt-for-assets swaps and diplomatic positioning that preserve optionality for a post-settlement phase in which US control is contested. China's adaptive playbook across sanctioned and near-default states is the pattern our China 2026 assessment maps at portfolio level.
The wider network framing hardened in July. The State Department's 20 July publication of a 100-page report, Cuba: Capital of 21st-Century Communism, alleges a decades-long covert network inside the United States built through espionage, ideological influence and activist cultivation, with Secretary Rubio describing Havana as orchestrating influence operations against US politics and national security; Cuba rejected the document as a "latest fallacy" manufacturing pretexts for continued economic warfare. The escalation ladder extends below it: the June indictment of Raúl Castro, Cuba's 24-hour blackouts generating migration pressure on the US border, and the ambassador to the UN, Mike Waltz, refusing at a House Foreign Affairs hearing to take military options off the table when asked directly whether an invasion was contemplated — the same hearing in which Congressman Mark Pocan warned that the report reads as "a blueprint for an invasion" (CBS News, August 2026). Treasury's architecture bundles this file with the others: the IRGC's long-standing presence as a sanctions-evasion node, Rosneft's and Gazprom's diminished oil-sector exposure, Cuban intelligence services as connective tissue between Caracas and other regional actors — all treated as components of a unified adversarial network, as the theatre-level logic of our Iran 2026 report documents. The administration's framing risks conflating distinct threat streams into a monolithic narrative that drives policy toward confrontation — and a realistic possibility exists that a Cuba-centred escalation through 2027 subordinates the quieter file to a louder one, compressing whatever bandwidth remained for transition management.
For organisations with China-linked trade finance or regional infrastructure exposure: audit every credit instrument that touches the CDB loan book, since restructuring negotiations will convert bilateral debt into asset claims — ports, terminals, power — with counterparty risk migrating from Beijing to Caracas; track Cuba-file escalation signals (Castro prosecution milestones, blackout-driven border incidents) as your early-warning indicator for the region's overall coercive temperature; and assume that any Chinese participation in the reconstruction will arrive disguised as commercial neutrality — equipment, services, trading desks — precisely where compliance screening is weakest.
7. The Overstretch Problem: Three Theatres, One Military
The binding constraint on the country's future is manufactured in other theatres. The Pentagon has deployed over 50,000 service members to the Middle East (Wall Street Journal, 3 September 2026); F-16s from Spangdahlem and F-35s from RAF Lakenheath have been redeployed to CENTCOM; the US military has expended over 50,000 rockets, missiles and projectiles since 2022 across the Russia-Ukraine and Iran conflicts — with Northrop Grumman lifting its 2026 forecasts on 21 July on sustained multi-conflict weapons demand. The war with Iran has not paused for the hemisphere: strikes on 30 August targeted the Larak loading facility, two Saudi tankers were damaged in the Strait of Hormuz, and follow-on operations continued into 1 September (New York Times, 31 August 2026).
Through early September, Tehran announced a "prohibited zone" around the strait from the US naval blockade line to the loading ports, a Saudi-loaded tanker was prevented from leaving it, and analysts counted 27 missile strikes in the waterway between July and early September — while a US Navy-coordinated corridor widened through Omani waters sustains only about ten commodity transits a day (Al Jazeera, 8 September 2026; Kpler data). The economics bind as tightly as the force posture — benchmark crude near $92, strategic reserves drawn — which is precisely what gave the concession architecture its security rationale, as our Strait of Hormuz conflict analysis, our South China Sea grey-zone assessment and our Gulf States report all track as elements of one allocation problem.
The energy arithmetic makes the coupling explicit. Trump ordered in March the release of 172 million barrels from the Strategic Petroleum Reserve as Iran's closure of Hormuz triggered what the Energy Department describes as the largest supply disruption on record, Secretary Wright's plan spreading the drawdown over roughly 120 days. By late September the reserve sat at its lowest level in over four decades — roughly 305 million barrels entering August, against an authorised capacity of 714 million, with 352 million barrels withdrawn in four years across two wars — and pump prices hitting records, gasoline above $4 and diesel averaging $6.53 per gallon in late September, up 77% year-on-year (CNBC, 28 July 2026; EIA data; AAA, 22 September 2026). The GAO has warned that repeated drawdown-refill cycles can leach salt caverns into "undesirable shapes," and Siddharth Misra, a petroleum-engineering professor at Texas A&M University, places the practical operational floor near 250 million barrels. Economist Lutz Kilian completed the warning: "once inventories are for all practical purposes exhausted, demand destruction becomes the only response to a shortage of oil" (Reuters, 31 August 2026). Kevin Book of ClearView Energy Partners framed the strategic conclusion in market language: whether the barrels go directly into the reserve or are sold to fund domestic purchases, full replenishment "could take years" and risked being cut short by elections "at home and in Venezuela" (Reuters, 31 August 2026). And on 30 August, Trump posted that the SPR would be refilled with oil from the agreement, beginning "very shortly" (New York Times, 30 August 2026). The concession architecture is therefore not adjacent to the overstretch problem — it is that problem's answer: a hundred-year concession designed to backfill a hundred-day drawdown.
The governing commitment does not currently require large-scale military deployment — but it consumes bandwidth from the same pool: troops physically present at Simón Bolívar Airport, soldiers directing aid logistics, a Cabinet secretary negotiating in Caracas, sanctions enforcement architecture, and now the security envelope around 17 concessioned oil fields and a century-long equity position. The question the file poses is not whether Washington intends to sustain oversight — the agreement is a statement of intent — but whether the Iran theatre leaves the bandwidth to honour it. On the current force posture and expenditure rate, the answer is: not indefinitely, and not simultaneously across all three theatres without degrading one or more commitments — Defence Secretary Pete Hegseth has already scheduled the 50,000-strong Middle East presence, including elements of the 82nd Airborne Division, into 2027 (Wall Street Journal, 3 September 2026). It is likely that governance oversight in the republic degrades measurably through 2027 as Hormuz requirements compound — the degradation arriving not as a decision but as an accumulation of deferred reviews, unfilled liaison postings, and slower interdiction response times.
For organisations with exposure to US policy continuity: model the reconstruction's security envelope as a variable inversely indexed to Hormuz escalation — each sustained strike cycle in the Gulf should move your duty-of-care posture for operations in the country one notch toward self-reliance; monitor the CENTCOM deployment tempo and munitions drawdown disclosures as your leading indicators of oversight decay; and avoid capital commitments whose security assumptions cannot survive eighteen months of drifting American attention.
8. Venezuela 2026 State Collapse — Three Scenarios

Scenario A — The Encumbered Protectorate: Stabilisation Without Transition (Probability: ~45–50%).
The baseline compounds. The oil agreement holds; Chevron's $7 billion programme lifts the reconstruction metric toward its 600,000-bpd target while national production oscillates in the 1.2–1.4 million band; US oversight continues at moderate intensity; Rodríguez governs under renewable emergency cover with elections deferred to the 2028–2030 horizons already circulating in Washington; the negotiation rounds settle into a permanent near-agreement — judicial reform accords, media openings, frozen-asset arrangements — that legitimises the arrangement without transforming it. The September record already fits this path: two rounds concluded, procedural gains signed, no electoral timetable, the opposition's strongest figure excluded from the table. Humanitarian stabilisation proceeds at the minimum viable level — sufficient to prevent collapse, insufficient to attract investment beyond the licensed energy perimeter. China converts purchase flows to leverage management without rupturing; migration pressure persists as a chronic regional condition rather than an acute event. This is the stabilisation path for a system whose dysfunction has become self-financing — the zombie state not cured, but bankrolled.
This scenario is elevated by every documented vector: the agreement's alignment of US financial interest with political deferral, the administration's own electoral timelines, the opposition's demonstrated incapacity to mobilise, and the reconstruction cash flows that reward continuity — now reinforced by a negotiation format that absorbs opposition energy into procedure. It is reduced only by the fragility of its two pillars — the Pentagon's long-term commitment in a theatre it did not choose, and the legal durability of century concessions signed by a caretaker government whose very architecture remains contested between competing official descriptions.
This scenario holds unless: a Hormuz escalation of sustained intensity forces a triage decision that hollows out the oversight commitment; a successor or revolutionary court action in the United States or an international forum unravels the concession's legal architecture; or an intra-apparatus rupture — succession fight or military fragmentation — destroys the counterparty Washington is financing.
Scenario B — The Bandwidth Collapse: Overstretch Withdrawal and Institutional Decay (Probability: ~25–30%).
The Iran war compounds; US bandwidth degrades beneath the level the protectorate requires. Oversight lapses are not decided but accumulate — deferred reviews, stale interdiction, thinning liaison. The apparatus interprets reduced supervision as licence: hardliners consolidate, emergency cover becomes permanent, licensed operators face rising extraction from a state that no longer fears its monitor. Reconstruction slows within the band's lower edge; Chevron's target slips; port delays lengthen beyond thirty days. Chavista remnants test the margins — selective harassment of opposition networks, opportunistic renationalisation threats around the concession perimeter. Chinese leverage management shifts from patient to predatory as the defending power visibly wanes. The system drifts from financed stability toward hollowed-out decay — the zombie state losing its source of blood supply.
This scenario is elevated by the force-structure arithmetic in Section 7 — fifty thousand troops in CENTCOM, 27 missile strikes in the strait since July, a prohibited zone declared in September, no reset mechanism on the calendar — and by the historical pattern that empires abandon oversight commitments before they abandon the interests themselves. It is reduced by the Pentagon's newly acquired equity position, which converts oversight from discretionary policy into asset protection, and by the demonstrated feasibility of low-footprint management through the existing license architecture.
This scenario holds unless: a decisive ceasefire or de-escalation in the Iran theatre frees bandwidth and re-anchors oversight; or the concession economics perform so strongly that private security and commercial enforcement substitute for state oversight, mooting the bandwidth question.
Scenario C — Rupture: Fracture, Repudiation and Containment Failure (Probability: ~20–25%).
One or more escalatory triggers fire: the military fractures along factional lines exposed by the earthquake-response failure; a Chavista counter-movement challenges Rodríguez; a catastrophic infrastructure failure — refinery fire, pipeline rupture, tanker incident — overwhelms remaining capacity; or the political rupture arrives through the ballot box or the street, with a successor government repudiating the concessions as illegitimate — the legal time-bomb the opposition has already lit rhetorically. Mass migration surges across Colombian and Brazilian borders; regional governments deploy emergency measures; production drops sharply; the reconstruction thesis reprices overnight.
This scenario is elevated by the accumulation of unpriced structural stress: the command-and-control failure documented in the disaster response, the latent illegitimacy of caretaker-signed century concessions — an architecture whose terms are contested even between official descriptions — and the sheer number of armed actors now orbiting 65 billion barrels of concessioned reserves. It is reduced by every stakeholder's shared interest in avoiding it — Washington, Beijing, the apparatus, the majors all lose in rupture — by the opening of a judicial-reform channel inside the negotiation format, and by the two-decade-demonstrated resilience of the population itself, which has absorbed punishment beyond rupture thresholds without producing a regime-toppling dynamic.
This scenario holds unless: the opposition's legal challenge to the concessions is neutralised by an internationally brokered compensation framework; or the armed forces undergo externally supported professional reconstruction before the fracture lines propagate — neither currently visible on any timetable.
9. Implications
For financial institutions with sovereign and energy exposure. Segregate the two credit stories: licence-based operator exposure (recovering, priced, enforceable in New York) and sovereign/quasi-sovereign claims (unchanged, structurally impaired, dependent on a settlement that has been deferred indefinitely). Do not extrapolate the concession headline into sovereign-improvement trades — the state's fiscal position improves only to the extent it taxes licensed activity, and its institutions remain relay points for a survival logic rather than counterparties in their own right. Treat a Machado-aligned or rupture-successor repudiation of the concessions as the tail risk requiring sovereign-linked hedge cover through at least 2028; monitor CDB restructuring negotiations as the earliest indicator of Chinese strategic reappraisal.
For energy-sector investors and operators. Sequence license-derived value ahead of concession-dependent commitments. Benchmark every contract against the Pentagon's cost-of-production purchase right — a state-backed floor mechanism that re-prices any commercial negotiation over the country's crude. Stress-test project models against the 2030 strategic-reserve replenishment calendar, which governs the durability of the security envelope; against Rystad's sixteen-year, $183–185 billion full-reconstruction arithmetic; and against the 1.2–1.4 million-bpd band as your central production case through 2027. Require contractual stability clauses that survive a change of sovereign policy on the concession estate.
For oil-service providers and vendor financiers. The counterparty of record for drilling, equipment and field services is not Chevron — it is the joint-venture structure in which PDVSA remains a party, an enterprise kept solvent primarily by discounted Chinese purchases of 50–89% of exportable crude (Reuters analysis, 4 September 2026) and therefore hostage to their redirection. Extend supplier credit only against license-anchored payment streams collected offshore; price payment-delay risk off the documented thirty-day port delays, not industry norms; and treat any receivable touching a ministry or state enterprise as a claim on a transmission mechanism, not a debtor.
For crude traders and commodity financiers. The current equilibrium is the Chevron gap (308,000 → 269,000 bpd) that Vitol and Trafigura fill; the concessions and the Pentagon's purchase right re-price every commercial negotiation over these barrels for the rest of the decade. Treat concession-repudiation risk as treaty-arbitration risk, not commercial dispute risk: map the concession estate's investment-treaty protections against the caretaker-signature problem — a successor repudiating would litigate through BIT/ICSID channels where ownership of the state's consent, not the contract, is the issue. Position financing structures so that title risk from the unresolved NABEP stake discrepancy — compounded by the conflicting official descriptions of the US interest itself — is contractually allocated before it is judicially allocated.
For engineering, construction and procurement functions. The reconstruction pipeline is real — $37 billion of assessed direct damage against a $298 million funded appeal — and it will be executed under a state that cannot coordinate an evacuation. Commission independent seismic audits of every candidate site in the La Guaira coastal corridor before bid submission, not after award; structure cash flows and payment channels through the licensed JV perimeter rather than ministry-level counterparties; and model labour on the documented H1 2027 secondary-wave pattern — returnee and displaced-worker recruitment driven by reconstruction demand — as both a cost advantage and a compliance exposure. Price all post-October exposure on the assumption that the humanitarian general license lapses on 23 October and is not renewed on current terms.
For insurers, reinsurers and brokers. Reprice war-risk premia on Gulf–Caribbean routes at each Hormuz cycle before quoting any Venezuela-bound hull; benchmark cargo cover against the documented thirty-day port delays, not regional averages. Secure kidnap-and-ransom capacity for reconstruction personnel outside the licensed perimeter; underwrite coastal assets only against independent engineering surveys — the government data-reliability deficit means real losses are invisible to underwriting statistics. Insert the 23 October humanitarian-general-license expiry into every warranty-compliance calendar for assistance-linked programmes.
For organisations with supply-chain and Andean-corridor exposure. Build the secondary displacement wave into H1 2027 planning — timed to reconstruction labour demand and aftershock housing condemnation, not to humanitarian catastrophe. Screen every reconstruction-chain counterparty against the sanctions lattice quarterly; treat transaction-level authorisation fluidity as permanent. Monitor Colombian border-province absorption metrics — the conversion point where displacement becomes regional operational risk — and price duty-of-care overheads on the assumption that state emergency response remains absent for the planning horizon.
For compliance and legal functions. Model the five-jurisdiction lattice as a single exposure surface. Insert jurisdiction-shift, sanctions-scenario and successor-government clauses into every Venezuela-adjacent agreement; treat any counterparty two degrees removed from designated networks as designated-in-waiting. Track the Hellerstein docket and appellate clock as the generator of asset-attachment risk extending well beyond the named defendants.
For organisations with personnel and duty-of-care exposure. Adopt expeditionary posture assumptions outside the licensed energy perimeter: self-sufficient medical evacuation, redundant communications, no reliance on state emergency response. Site every facility against the seismic zoning of the coastal corridor around La Guaira before reconstruction-related commitments. Treat NGO and IFRC field reporting as ground truth; the official casualty and damage series has lagged independent tallies by thousands throughout the recovery.
For boards and public-affairs functions. Rewrite the stakeholder map around the autumn reality: the decisive relationships are now in Washington's national-security energy bureaucracy and the Chevron-NABEP commercial perimeter, not in Caracas ministries. Prepare a considered position on the concession-legitimacy question before it is forced upon you — a successor-repudiation scenario would put every participant in the reconstruction chain inside a contested-sovereignty argument within a news cycle. Track the two genuine repricing triggers continuously: Hormuz escalation tempo, and the legal durability signals around the concession architecture — court filings, negotiation-round attendance, opposition statements.
10. Core Analytical Judgment
The country's defining condition is not dictatorship, nor collapse, nor reconstruction. It is that every variable that matters is now coupled to a decision made in someone else's capital — and for the first time, one of those decisions is commercial. The trial docket couples the transition to a Manhattan courtroom. The electoral timetable couples to a Washington internal debate priced in oil-equity terms. The reconstruction couples to a Hormuz strike schedule. Beijing's engagement couples to a loan book denominated in barrels it can no longer buy. The republic governs none of these variables. It hosts them.
The January operation succeeded in removing the man. It has not succeeded in anything else — and the September settlement, by giving the surviving apparatus a paying tenant, converted the failure into an institution. The rounds of talks that followed do not contradict this; they confirm it, converting opposition energy into procedural accords — a court-reform agreement, a few reopened broadcasters — while every question of power is deferred to a horizon that recedes as it is approached. The zombie state was a transition mechanism's absence; it is now a business model with equity holders. This is the coupling that matters most for boards: American bandwidth, Chinese patience, Chavista survival and Chevron's capital programme have all converged on the same quiet preference — that nothing be decided, and that the wells keep pumping.
The intervention did not choose between regime change and restoration. It chose custody. The window in which a managed transition remains possible has not closed — but it is narrowing at a pace determined less by the country's dynamics than by how long the United States can sustain concurrent strategic commitments across three theatres. The scenarios are not forecasts of fate but maps of the couplings; the triggers are the joints failing.
Plan for the protectorate; stress-test against the rupture. The state was decapitated for its oil and is being kept breathing for the same reason — and an organism kept alive for its organs is neither a patient nor a partner. Everything this collapse generates — migrant flows, energy-market distortion, geopolitical opportunity for patient powers — is still being paid in instalments that compound.
---
If your organisation is assessing exposure to Latin American energy markets, Venezuelan sanctions frameworks and concession legality, regional supply chains and displacement dynamics, or the intersection of US strategic commitments across multiple theatres, CES Intelligence maintains continuous situational awareness and can provide bespoke risk assessments, crisis stress-testing, and board-level briefings.
Want more analysis like this?
Bespoke advisory available on request.
Thierry Marquez — Founder & Principal Advisor, CES Intelligence
+33 (0)9 55 16 54 98 →
DISCLAIMER
This analysis is provided for informational and strategic planning purposes only. It is not investment advice, financial advice, or legal advice, and it should not be treated as such. Probability assessments reflect the analyst's calibrated judgment based on available open-source intelligence as of the date of publication and are subject to revision as new information emerges. Some quantitative estimates and reported events are based on regional sourcing that may evolve as additional confirmation becomes available.